Empire Energy Capital

Tax treatment

A deduction reduces taxable income. It is not a refund.

Potential tax benefits can improve after-tax results, but the underlying interest must stand on its own merits. A $100,000 deduction is not a $100,000 payment from the Treasury.

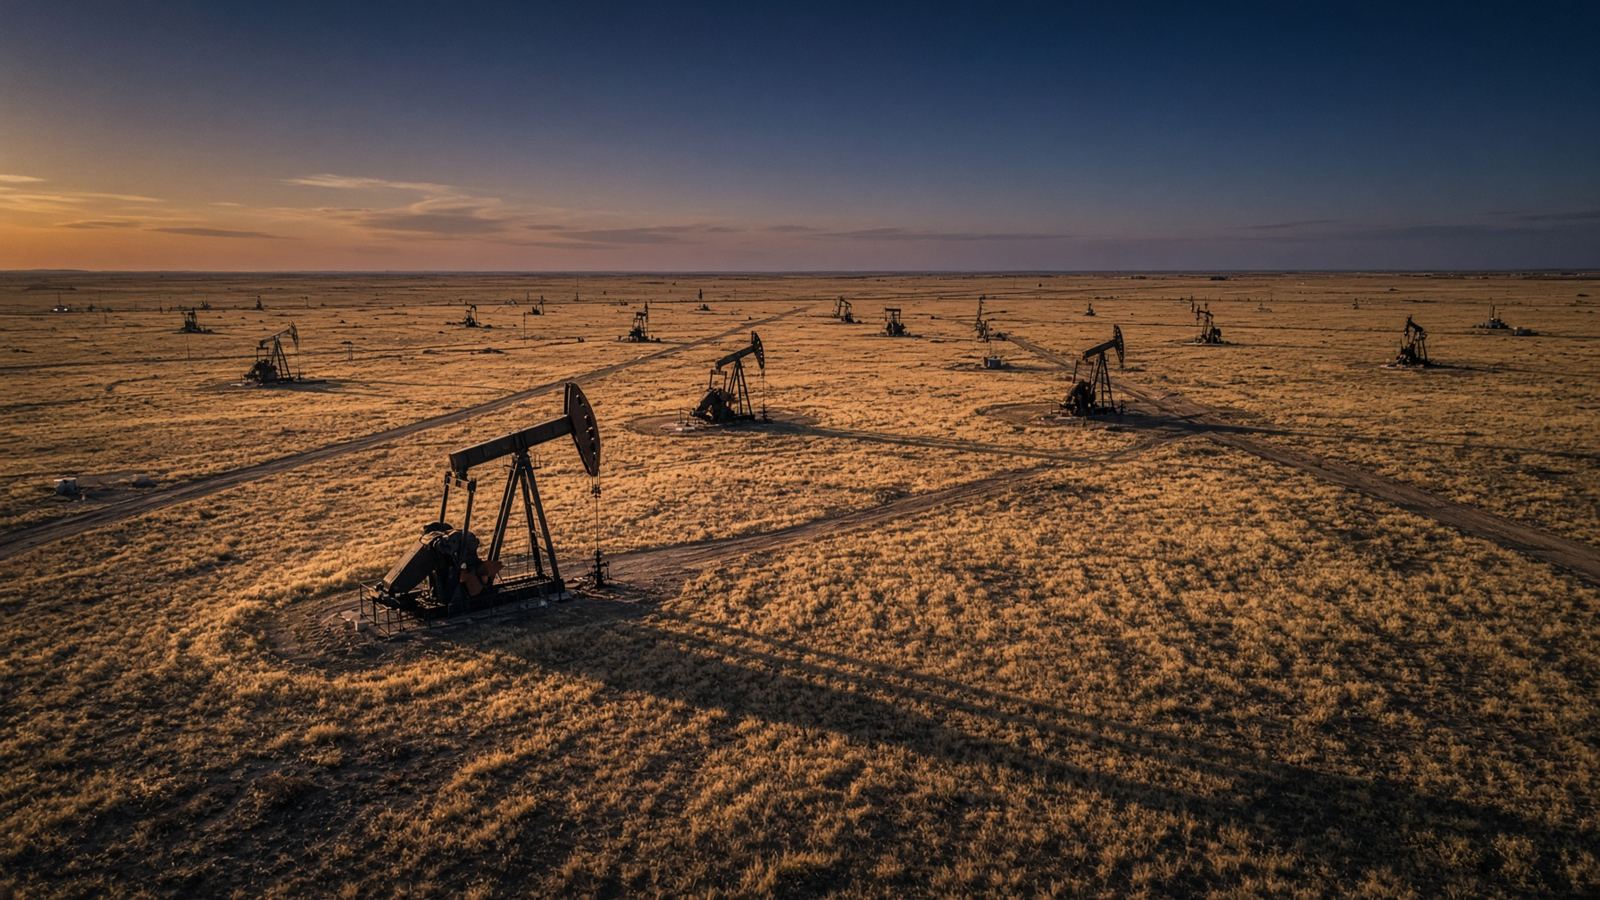
Producing field at dusk

Three building blocks

IDC

Intangible drilling costs

Eligible drilling and development expenditures without salvage value — qualifying labor, fuel, supplies, and services. Federal law permits an election to expense eligible IDC under §263(c) and Treas. Reg. §1.612-4. An advertised IDC percentage is a project assumption, not a universal statutory rate. Sending money before December 31 does not by itself establish a current deduction.

Equipment

Bonus depreciation

Tangible property with physical value. Current federal law generally restores 100% bonus depreciation for eligible property acquired and placed in service after January 19, 2025. Buying property and placing it in service are separate requirements. Eligible IDC plus eligible equipment deductions can, in some projects, cover most qualifying drilling and equipment costs in the same year. That does not mean every subscribed dollar is immediately deductible.

Resource

Depletion

Depletion recognizes consumption of the mineral as production is sold. Eligible independent producers and royalty owners may qualify for percentage depletion, commonly at a 15% statutory rate for qualifying production, subject to limits. It is not a statement that 15% of every distribution is tax-free. Buying a producing interest does not allow the buyer to claim the seller’s old drilling deductions.
Structure determines whether a loss is usable

The working-interest exception to the passive-activity rules applies to interests held directly or through an entity that does not limit the owner’s liability. It does not automatically apply to every LLC or joint venture. Even a nonpassive loss may be limited by basis, amounts at risk, and excess business loss rules. Disallowed losses do not all become an unrestricted deduction the next year. A CPA should model the full return before an interest is sized to offset salary or other income.

IDC can interact with alternative minimum tax. There is no single income threshold at which an oil and gas deduction becomes unusable. Federal and state results must be calculated separately. Cash distributions and taxable income can differ; a partnership generally reports tax items on Schedule K-1.

Sale proceeds are not automatically tax-free. Prior deductions can reduce basis. Section 1254 can require ordinary-income recapture of certain prior IDC and depletion to the extent of gain. Accelerating a deduction can provide a timing benefit. Its lifetime value depends on later income, sale taxes, and what is done with cash retained.

Primary authorities

Working interest · Examples