One
Geology
What supports expected output, decline, and recoverable volumes?
Examples
They are not fund terms, industry averages, expected returns, or individualized tax advice. Tax treatment and operating cash are shown separately on purpose.
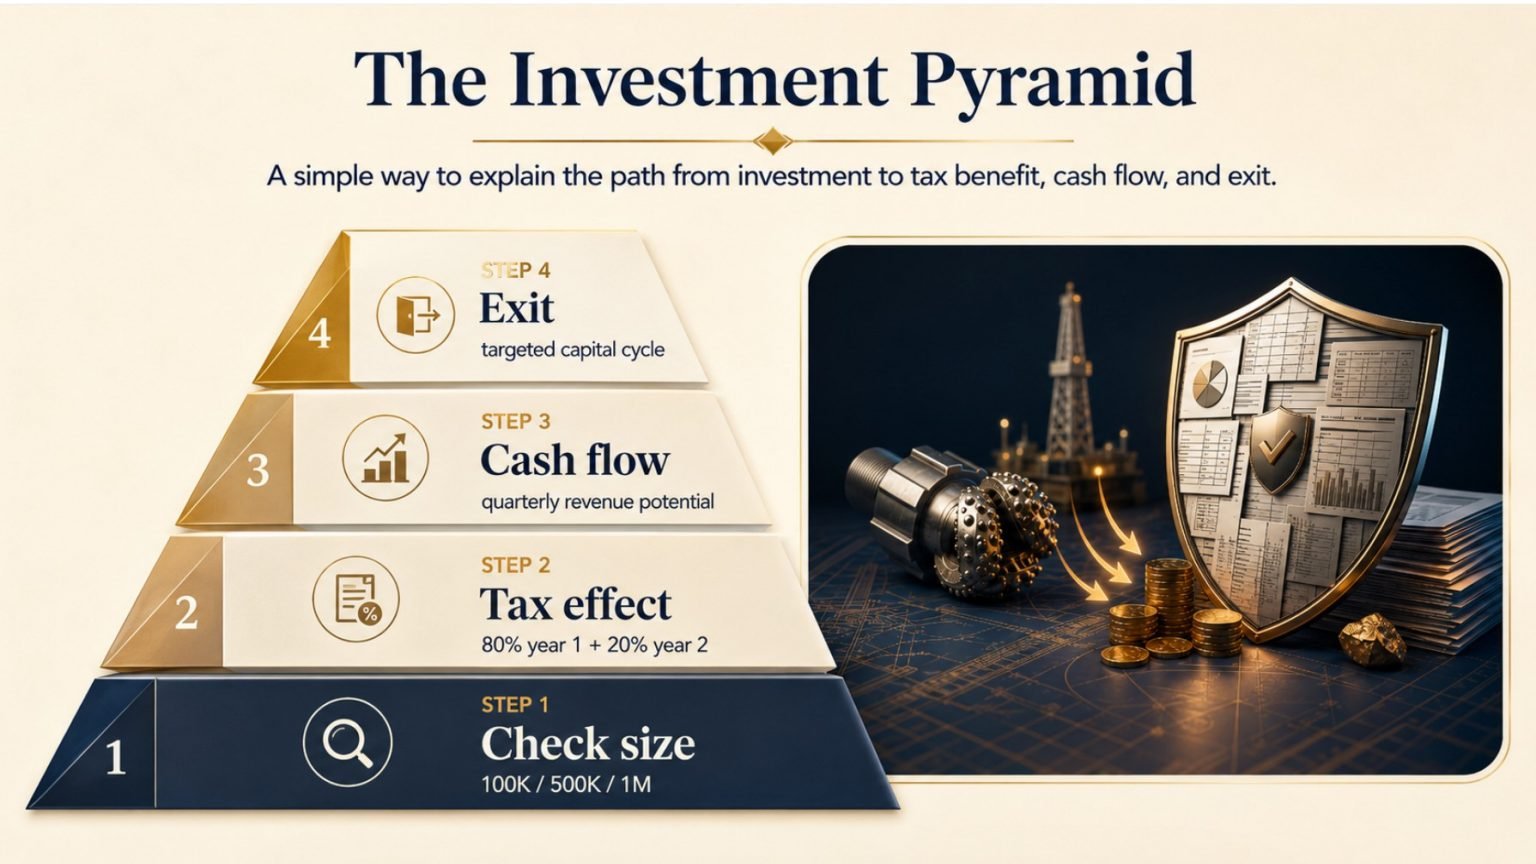
Assume $100,000 is invested and the stated deduction is fully usable at the illustrative marginal rate. Ignore bracket changes, AMT, state differences, financing, and subsequent taxes for this limited calculation.
| Usable deduction | Assumed rate | Tax reduction | Outlay less tax reduction |
|---|---|---|---|
| $80,000 | 30% | $24,000 | $76,000 |
| $80,000 | 40% | $32,000 | $68,000 |
| $100,000 | 30% | $30,000 | $70,000 |
| $100,000 | 40% | $40,000 | $60,000 |
The full $100,000 is still committed. A tax reduction may arise later and does not reduce what the operator can lose. The final column is an arithmetic net outlay, not market value or a limit on future liability.
Assume $100,000 invested, total operating distributions of $60,000 over an unspecified holding period, and sale proceeds of $50,000 after selling expenses, with no additional capital calls. Investment receipts total $110,000 — a $10,000 pretax gain, or 10% cumulative pretax return. That is not an annual return.
For a separate hypothetical tax overlay, assume a $30,000 initial tax reduction, $15,000 tax on operating income, and $12,000 tax on the sale. Combined cash result: $60,000 + $50,000 + $30,000 − $15,000 − $12,000 − $100,000 = $13,000. Do not describe $40,000 of tax savings plus $20,000 of distributions as a 60% operating return. One item is a personal tax effect; the other is investment cash, which may include recovery of capital.
If investment receipts total only $35,000 and an assumed net lifetime tax benefit is $25,000, the combined result on $100,000 invested is a $40,000 loss. A tax benefit cannot establish that a project is profitable.
One
What supports expected output, decline, and recoverable volumes?
Two
Does the model survive lower realized prices, higher costs, and capital calls?
Three
What deductions are actually usable, when, and what happens on a later sale?